FDIC-Insured - Backed by the full faith and credit of the U.S. Government
F&M Bank 
Online Banking

Download our app
Just scan the QR code and grab our mobile banking app—it’s super easy and makes banking a breeze!
Download our app
Tap the badge and grab our mobile banking app—it’s super easy and makes banking a breeze!
not featured
2026-10-20
Business & Ag Insights
published
5 Ways to Help Protect Your Business When Accepting Payments
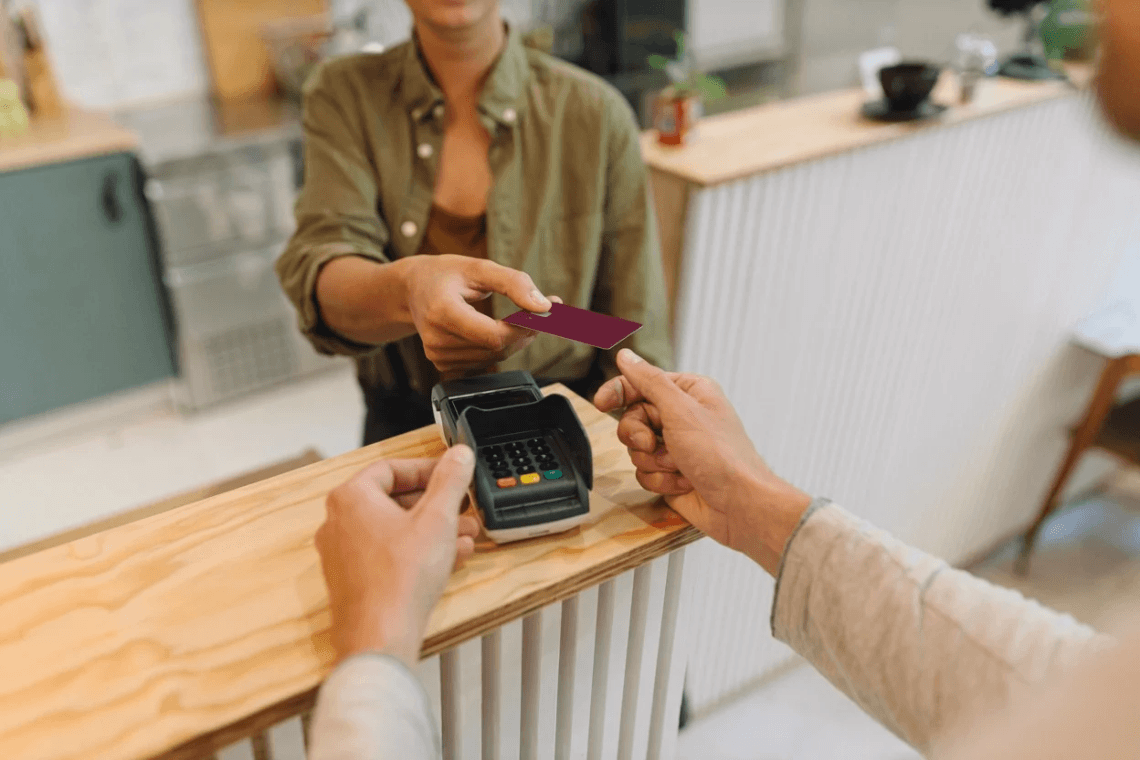
Accepting payments is an everyday part of running a business. Unfortunately, so is managing the risk that comes with them.
Payment fraud can take many forms, from a stolen card used in person to a fraudulent online order or a customer disputing a legitimate purchase. And the impact isn't always limited to the transaction itself. Fraud and chargebacks can create additional administrative work, lost inventory, customer issues, and interruptions that take your attention away from running your business.
The good news is that businesses don't have to approach payment security alone. Here are five areas worth considering.
1. Use Secure Payment Technology
How a payment is accepted matters. EMV chip and contactless payment technology can provide greater security than older payment methods, while secure payment gateways and other security tools can help businesses manage risk when accepting payments online.
If you're still relying on older equipment or processes, understanding what newer technology offers can be a good first step.
2. Pay Attention to Online and Card-Not-Present Transactions
Online, phone, and other card-not-present payments can present different risks than an in-person transaction. Tools such as address verification, secure payment gateways, tokenization, and fraud monitoring can provide additional layers of protection depending on your payment environment.
The goal isn't to make it harder for legitimate customers to pay. It's to create a secure payment experience while helping identify activity that may require a closer look.
3. Understand PCI Compliance
If your business accepts credit or debit cards, you've probably encountered the term PCI Compliance.
PCI Compliance refers to security standards designed to help businesses protect cardholder information when accepting, processing, storing, or transmitting payment card data.
The specific requirements can vary depending on your business and how you accept payments. You don't need to become a payment security expert, but staying current with your requirements is an important part of protecting both your business and your customers.
4. Keep Good Transaction Records
Sometimes fraud prevention isn't enough, and a transaction is disputed. Maintaining clear records such as receipts, invoices, shipping confirmations, and relevant customer communications can make it easier to respond when a chargeback occurs.
Sometimes fraud prevention isn't enough, and a transaction is disputed. Maintaining clear records such as receipts, invoices, shipping confirmations, and relevant customer communications can make it easier to respond when a chargeback occurs.
Good recordkeeping may not prevent a dispute, but it can help reduce the disruption of gathering information after the fact.
5. Review Your Payment Security Periodically
Businesses change, and so do the ways they accept payments.
Maybe you've added ecommerce, started sending payment links, introduced recurring billing, or upgraded your point-of-sale system. As your payment environment changes, your security needs may change with it.
Periodically reviewing your payment setup can help you understand the security features you're currently using, identify potential gaps, and make sure your approach continues to fit your business.
Protection Is About More Than the Transaction
No payment solution can eliminate fraud entirely. The goal is to reduce unnecessary risk and minimize the disruption when something does happen.
A strong payment strategy considers not only how you get paid, but also how those payments and your customers' information are protected.
If it's been a while since you've reviewed your payment security, our Merchant Services team can help answer questions about your current setup, PCI Compliance, and the tools available to help protect your business.
Contact Carly Knicely to learn more about our Merchant Services program.